
Homeownership comes with more responsibilities than making monthly mortgage payments. One of the biggest costs many first-time homeowners overlook is home taxes. Rates can rise, fall, or stay steady depending on your area, and understanding why helps you plan ahead. This guide on Home Taxes for Beginners explains how property taxes work, how they’re calculated, and what tax benefits you may qualify for. It’s written for new buyers and renters thinking about becoming homeowners, offering simple explanations without the confusing terminology.
Understanding Property Tax Basics for Beginners
Property taxes shape your yearly home expenses and play a major role in long-term budgeting. They’re tied to your home’s value and your local government’s yearly spending plans. Understanding these basics helps you anticipate changes and stay prepared.
What Is Property Tax?
Property tax is a yearly fee homeowners pay based on their property’s assessed value. Local governments – such as cities, towns, and counties—use these taxes to fund services like:
- Schools
- Fire departments
- Road repairs
- Libraries
- Local infrastructure
Tax amounts vary by area and depend on reassessments, property improvements, and local budgets.
How Property Taxes Are Calculated (Home Taxes for Beginners Breakdown)
Property taxes change each year based on two core factors: your home’s assessed value and your local tax rate. Understanding the calculation helps you manage rising and falling taxes with confidence.
Assessed Value vs. Market Value
Your home has two different values:
- Market value: What your home could sell for today (Zillow or Realtor data can estimate this).
- Assessed value: The value your local assessor uses to calculate your tax bill, usually a percentage of market value.
Reassessments happen yearly or every few years depending on your area.
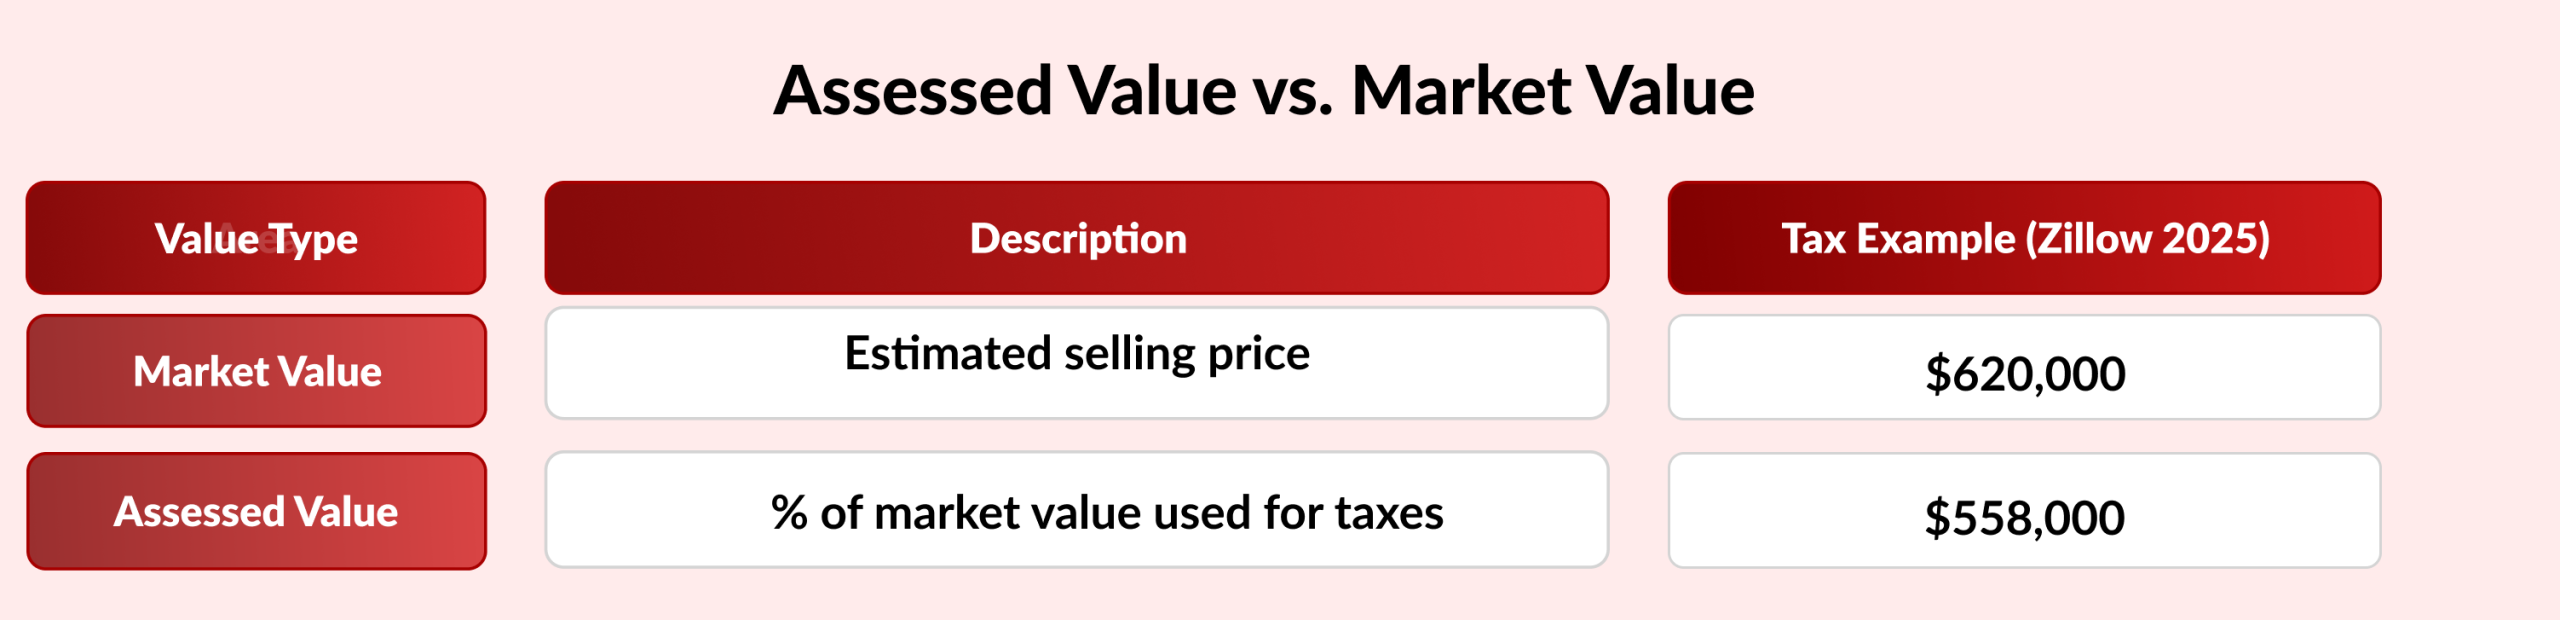
Source: Zillow 2025
Understanding Tax Rates & Millage
The formula is simple:
Assessed Value × Tax Rate = Annual Property Tax
Many areas use millage, where one “mill” equals $1 tax per $1,000 of assessed value.
Higher millage rates reflect larger local budgets or more public services.
How to Pay Property Taxes (Home Taxes for Beginners Guide)
Payment schedules differ by area, but the methods are generally the same everywhere.
Paying Taxes Through Your Mortgage Escrow
Escrow breaks your yearly taxes into monthly amounts added to your mortgage payment. Your lender pays the tax bill on your behalf. This method prevents missed payments and keeps your loan in good standing.
Paying Taxes Directly
If you pay taxes yourself:
- Payments may be due annually, semiannually, or quarterly
- Set reminders or use automatic payments
- Track due dates to avoid penalties
How Beginners Can Lower Their Property Tax Bill
Many homeowners reduce their tax bills by reviewing assessments, understanding exemptions, and taking advantage of local programs.
Check Your Assessment for Errors
Look for:
- Incorrect square footage
- Incorrect building details
- Missing updates or outdated features
Correcting errors often lowers your bill.
Appealing an Overvaluation
If your home’s assessed value seems too high:
- File an appeal with your assessor’s office
- Provide comparable home sales
- Use recent market data to support your case
Even a small reduction can lower your yearly taxes.
Exemptions & Abatements for Homeowners
Depending on your area, you may qualify for:
- Primary residence exemptions
- First-time homeowner reductions
- Veteran or senior exemptions
These programs vary but may lower your tax burden.
Insert Image Here: Bar chart — “Common Ways Homeowners Reduce Taxes”
What Happens When You Don’t Pay Your Property Taxes (Home Taxes for Beginners)
Missing tax payments leads to penalties that grow over time.
Tax Liens Explained for Beginners
A tax lien is a legal claim on your home when taxes remain unpaid. It affects:
- Your title
- Your ability to refinance
- Your ability to sell
The tax debt must be cleared before any transfer happens.
Long-Term Penalties
Consequences may include:
- Interest and penalties
- Risk of tax sale by the municipality
Staying current prevents these issues.
Real Estate Tax Planning Basics (Beginner Edition)
Learning how taxes work helps homeowners plan ahead and avoid unexpected costs.
Why Tax Planning Matters
Tax planning helps you:
- Estimate your yearly home expenses
- Prepare for reassessments
- Track improvements that may reduce taxes
- Understand potential deductions
Key Tax Benefits for Real Estate Investors
Even beginners exploring rental properties benefit from knowing basic tax breaks.
Depreciation Explained Simply
Depreciation allows you to deduct part of the property’s value each year, lowering your taxable income.
1031 Exchange Overview
A 1031 Exchange lets you defer capital gains tax by reinvesting into another investment property.
Deductible Rental Expenses
Common deductible expenses include:
- Repairs
- Maintenance
- Insurance
- Utilities
- Travel for property management
How to Calculate Your Tax Burden When Selling a Home
Understanding your potential tax responsibility makes the selling process easier.
Understanding Cost Basis
Cost basis includes:
- Your purchase price
- The value of improvements
Tracking improvements helps reduce taxable gains.
Short-Term vs. Long-Term Capital Gains
- Short-term: Owned for 1 year or less, taxed as regular income
- Long-term: Owned for more than 1 year, with lower tax rates
Insert Image Here: Flowchart — “How Capital Gains Work”
Common Tax Mistakes Beginners Should Avoid
Avoiding these mistakes saves money and prevents future problems.
Missing Reassessment Notices
You miss the chance to challenge errors.
Not Appealing Overvalued Assessments
Overvalued homes lead to higher taxes.
Forgetting Deductions
Many homeowners overlook deductions they qualify for.
Poor Documentation
Missing receipts or improvement records creates issues when selling.
Quick Tips to Stay Ahead on Home Taxes
Simple habits help you stay organized year-round.
Annual Assessment Review
Check your assessed value for accuracy.
Keep a Digital Folder of Expenses
Store tax documents, receipts, and improvement records.
When to Contact a Real Estate Tax Professional
If you plan to buy, sell, or invest soon, understanding local tax trends becomes helpful.
For market value questions or guidance on area-specific tax patterns, many homeowners turn to the local real estate agents in Newton. Their local expertise helps homeowners understand how taxes may affect future decisions.
Frequently Asked Questions (FAQ)
Why do home taxes keep rising or falling each year?
Taxes change based on market value, reassessments, and local budgets.
How often are property taxes reassessed?
Most areas reassess yearly or every 2–3 years.
Can first-time homeowners get tax breaks?
Yes, depending on local programs.
Do renters need to worry about property taxes?
Indirectly, because rising taxes may influence rent.
Conclusion
Property taxes shape your long-term home expenses, but learning the basics helps you stay in control. With planning, accurate assessments, and available deductions, you can manage your tax responsibilities confidently. And when you’re preparing to buy or sell, the Centre Realty Group team provides helpful insight into market values and area tax trends, supporting informed decisions without pressure.
Recent Comments